Buying your first home is the biggest financial decision most families make, and in Hulhumalé it comes with its own rules: HDC leases, bank equity requirements, pension schemes and a busy resale market. This step-by-step guide explains how to buy a flat in Hulhumalé as a first-time buyer, what it costs, and how to avoid the mistakes that catch people out.
This is general guidance. Rules, rates and fees change, so confirm details with your bank, HDC and a lawyer before committing.
Step 1: Work out what you can afford
Start with your monthly income, not the price of the flat you like. Banks look at how much of your income goes on debt repayments, called the debt service ratio. BML, for example, generally allows repayments up to about half of net income, while some lenders set stricter limits.
As an example, a flat costing MVR 3 million with a 20% deposit and a 25-year BML loan at around 9% means a repayment of roughly MVR 20,100 a month. At a 50% limit, that needs a household income of around MVR 40,300 a month. Read the full breakdown in how much income you need to buy a flat, and try different prices in the loan calculator.
Joint applications with a spouse or family member can increase what you can borrow.
Step 2: Plan the deposit and extra costs
The deposit (equity) is the part of the price you pay yourself. Requirements vary by bank and product, typically from 5% to 30%. On a MVR 4 million flat, 10% is MVR 400,000 and 20% is MVR 800,000.
Your pension can help. Under the MPAO housing scheme, part of your Maldives Retirement Pension Scheme savings can be pledged as security with a participating bank, reducing the cash you need. It is not withdrawn as cash, and you can only use it once. See how to use your pension for a home deposit.
On top of the deposit, budget for:
- Bank processing and valuation fees.
- Legal fees for checking documents and drafting the sale agreement.
- HDC or council transfer fees, where they apply.
- Insurance required by the bank.
- Furniture, appliances and moving costs.
Step 3: Choose a bank and get pre-approval
The main home loan lenders are Bank of Maldives (BML), Maldives Islamic Bank (MIB, with Sharia-compliant financing) and HDFC Maldives. They differ in rates, equity, maximum term and how they treat income. Compare them in BML vs MIB vs HDFC home loans.
Ask for an indication of how much you can borrow before you start viewing. It tells you your real budget and makes sellers take you seriously. Typical documents include ID, salary slips, bank statements, employment letter and, for the self-employed, business accounts.
Step 4: Decide where and what to buy
Hulhumalé has two very different halves. Phase 1 is established and convenient; Phase 2 is newer with more towers and future growth. Read Phase 1 vs Phase 2 and the best neighbourhoods for families.
Then decide between:
- Resale flats: you can see exactly what you are buying and move in sooner.
- New or off-plan flats: modern, sometimes cheaper with payment plans, but with completion and developer risk. See buying off-plan.
- Government schemes: if you qualify, social housing such as Hiyaa flats can be far cheaper. See Hiyaa flats explained.
Browse flats for sale and set an alert so new listings that match reach you by email. On our site, Hulhumalé flats currently range from about MVR 3.6 million to over MVR 7 million.
Step 5: View and compare
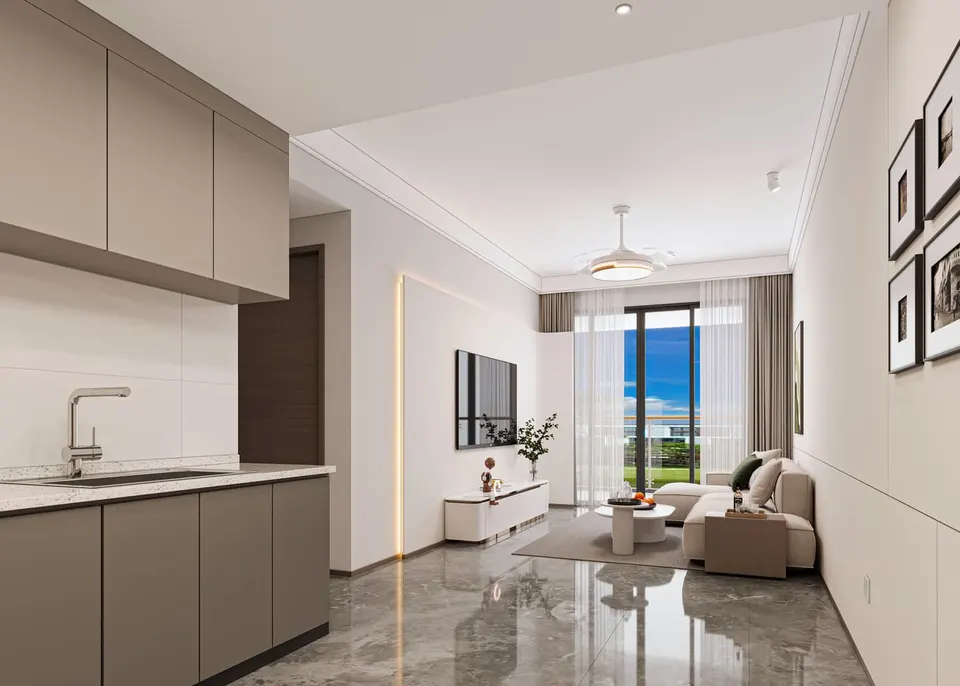
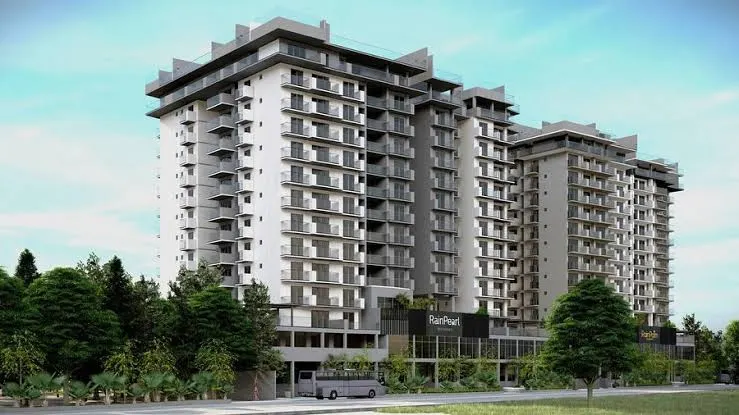
 For sale nowFrom MVR 3.6M1+1 Bedroom Apartments at Bayfancy · Hulhumalé
View at least three or four flats. For each, note the price per square foot, floor, lift, parking, view, building age and service charges. Look for damp, cracks, water pressure and the condition of air conditioners. Ask neighbours about the building. Our price per square foot data helps you tell a fair price from a high one.
Step 6: Check the paperwork before you pay
This is the most important step. Ask for, and have a lawyer check:
- The seller's ID and the documents proving their right to the flat (lease, title or allocation documents).
- Whether the property is mortgaged to a bank. If so, how the loan will be cleared at completion.
- Any HDC or scheme restrictions on resale, such as minimum holding periods or eligibility rules for buyers.
- Unpaid service charges, utility bills or HDC payments.
- That the flat matches the approved plans and the area stated.
- For inherited flats, that all heirs agree to the sale. See inheriting property in the Maldives.
Scams exist. Never pay a deposit to someone you have not verified, and be wary of prices far below the market. Read seven warning signs of a property scam.
Step 7: Agree the price and sign a sale agreement
Negotiate using comparable listings. Once agreed, sign a written sale agreement that states the price, deposit, payment schedule, what is included (furniture, AC units, parking), completion date, and what happens if either side backs out or the loan is refused. A small holding deposit is common; make sure it is refundable if the bank does not approve your loan.
Step 8: Complete the loan
Submit the sale agreement to your bank. The bank will value the flat, check the documents and issue a formal offer. Read the offer carefully: rate, whether it is fixed or variable, term, fees, insurance and early repayment rules. The bank will usually register a charge over the property as security.
Step 9: Transfer and registration
The transfer is registered with the relevant authority, with HDC involvement for many Hulhumalé properties. The seller is paid, usually by the bank directly, and the property is recorded in your name. Keep copies of every document. Read property transfer and registration for the process and fees.
Step 10: Move in
- Transfer electricity and water accounts into your name and take meter readings.
- Register with the building management and pay any service charge.
- Check insurance is in place.
- Change locks if keys have been in many hands.
Should you buy now or keep renting?
There is no universal answer, but a simple test helps. Compare the monthly rent for the flat you want with the monthly loan repayment plus service charges, insurance and maintenance. If the cost of owning is close to the rent, and you expect to stay at least five to seven years, buying usually makes sense, because each repayment builds your own equity. If you might move abroad, change jobs or need a bigger home within two or three years, the costs of buying and selling can outweigh the benefit.
A 2-bedroom Hulhumalé flat that rents for around MVR 19,000 a month might sell for MVR 4.2 – 5.7 million. With a 20% deposit and a 25-year loan around 9%, a MVR 4.5 million flat costs roughly MVR 30,200 a month to repay, well above the rent. Many first-time buyers therefore start with a smaller flat or a larger deposit. See current Hulhumalé rents to compare.
Five first-time buyer mistakes
- Looking before knowing the budget. Falling for a flat you cannot finance wastes time and money.
- Forgetting extra costs. Fees, furniture and moving can add 3–5% of the price.
- Skipping legal checks. A lawyer's fee is tiny compared with buying a flat with a problem title.
- Paying a non-refundable deposit before loan approval.
- Stretching to the maximum. Leave room in your budget for rate rises and life changes.
Frequently asked questions
How much deposit do I need to buy a flat in Hulhumalé?
It depends on the bank and loan. BML has offered housing finance with a minimum equity of 5% of the project cost, while 10–20% is common. Your pension may help through the MPAO housing scheme.
Can I use my pension to buy a flat?
Yes, under the MPAO housing scheme part of your retirement savings can be pledged as security for a home loan with a participating bank. It is not paid out as cash. See our pension guide for details.
Do I need HDC approval to buy a resale flat in Hulhumalé?
Many Hulhumalé properties sit on land allocated by HDC, and transfers often need HDC involvement and fees. Check the specific lease or scheme rules with HDC before you pay.
How long does it take to buy a flat?
A straightforward cash purchase can complete in weeks. With a loan, allow one to three months for approval, valuation and paperwork.